• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer
MacElree Harvey, Ltd.

MacElree Harvey, Ltd.

Initiative in Practice

  • Home
  • Legal Services
        • Banking & Finance Law
        • Business & Corporate Law
        • Criminal Defense
        • Employment Law
        • Estates & Trusts Law
        • Family Law
        • Litigation Law
        • Mediation and Arbitration
        • Personal Injury Law
        • Real Estate & Land Use Law
        • Tax Law
  • Our Team
        • Joseph A. Bellinghieri
        • Hiruy Y. Berhane
        • Patrick J. Boyer
        • Krzysztof M. Bozentka
        • Jeffrey P. Burke
        • Robert A. Burke
        • Matthew C. Cooper
        • Marie I. Crossley
        • Pilar Diaz
        • Harry J. DiDonato
        • Jaycie DiNardo
        • Caroline G. Donato
        • Nicholas S. Eisel
        • Sally A. Farrell
        • Brian J. Forgue
        • William J. Gallagher
        • Patrick J. Gallo, Jr.
        • Mary Kay Gaver
        • J. Charles Gerbron, Jr.
        • Leo M. Gibbons
        • Joseph P. Green, Jr.
        • Frank W. Hosking III
        • Katherine A. Isard
        • Peter E. Kratsa
        • Mary E. Lawrence
        • Daniel R. Losco
        • Michael G. Louis
        • John F. McKenna
        • Matthew M. McKeon
        • Lou Mincarelli
        • Brian L. Nagle
        • Lance J. Nelson
        • Timothy F. Rayne
        • Michael C. Rovito
        • Duke Schneider
        • Andrew R. Silverman
        • Ashley B. Stitzer
        • Patrick L. Ware
        • Jeremy A. Whalen
        • Natalie R. Young
  • About Us
    • Our History
    • Our Approach
    • Social Responsibility
    • Testimonials
  • Careers
  • News & Updates
    • Articles by Our Attorneys
    • News
    • Podcasts
    • Videos
    • Newsletters
  • Offices
    • Centreville, DE
    • Kennett Square, PA
    • West Chester, PA
  • Contact
  • (610) 436-0100

Andrew Silverman

Taxation of Foreign Investment in Delaware Entities

September 4, 2019 by Andrew R. Silverman, Esq.

taxation ID 136274785 © Pattanaphong Khuankaew | Dreamstime.com

Foreign investors and entrepreneurs who would like to do business in the United States are confronted with a number of legal decisions to make and, if not familiar with the local law, these decisions can be quite daunting. One question that invariably comes up for foreign investors who desire to form a Delaware entity is this: how will it be taxed?

Is the income taxable? 

Your entity will be taxed if two conditions are present: (1) the entity is engaged in the sale of goods and services in the United States (referred to as “engaged in trade or business” or “ETB”); and (2) the entity earns income that is effectively connected with United States sources (such income, is often referred to as “effectively connected income” or “ECI”).

TIP: If your entity is subject to taxation in the United States, you may be able to offset the taxes by carefully planning how distributions will be made to the ultimate beneficial owner (i.e., the foreign shareholders or partners) and by taking advantage of the numerous tax treaties to which the United States is a party.

Taxation of Delaware C-Corporations

Federal Taxation

If your entity is a corporation and is subject to tax in the United States, it will be subject to double taxation. This means that the ECI will be taxed once upon receipt by the corporation and then a second time if it is later distributed to stockholders (such as through a dividend or liquidation). The current federal corporate tax rate is 21 percent of the ECI.

Delaware Taxation

Generally, Delaware will only assess a tax on ECI that is attributable to Delaware sources or if it has assets, employees, or activities in Delaware.

Taxation of Delaware LLCs and Partnerships

Federal Taxation

Generally, the federal government does not impose a tax on ECI that is received by the LLC or partnership but it does tax the members or partners directly. Thus, while an LLC or partnership can avoid double taxation, the members or partners will be exposed to federal and state and local taxes and will need to file US tax returns that report worldwide income. This may not be ideal for various reasons.

In such cases, each member or partner may form a “blocker” corporation to hold its membership or partnership interest. In such cases, the blocker corporation and dividends to its ownership will be taxed but reporting requirements on the ultimate beneficial owner will be reduced.

Delaware Taxation

Delaware does not impose income taxes upon LLCs and partnerships; however, the state will impose a gross receipts tax on income from Delaware sources.

Any foreign person or entity that desires to do business in the United States through a Delaware entity is advised to partner with US-based lawyers and accountants who are familiar with the legal and tax requirements.
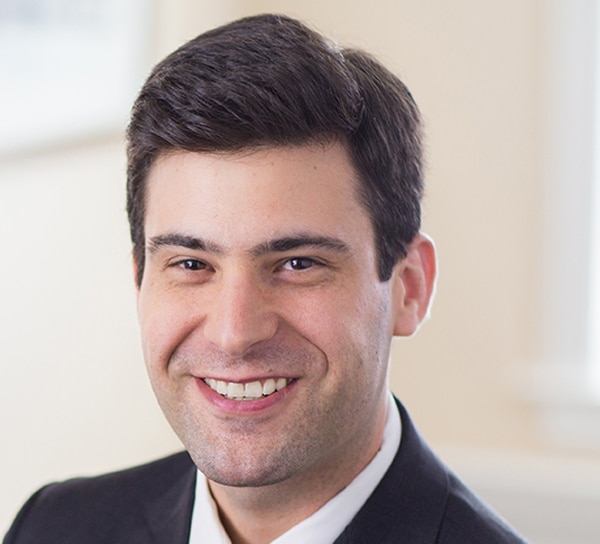

Andrew Silverman, Business Law

Andrew Silverman is an attorney in the firm’s Business Department whose practice includes complex corporate governance and financing matters. If you are a Delaware business owner and desire guidance, call (610) 840-0286 or email asilverman@macelree.com.
Filed Under: Articles by Our Attorneys Tagged With: Andrew Silverman, Delaware Business, tax law

How to Form a Delaware Corporation

August 15, 2019 by Andrew R. Silverman, Esq.

business incorporation - ID 113895525 © Andrei Rahalski | Dreamstime.com

By Andrew R. Silverman, Esquire-

Delaware is a proper jurisdiction for business incorporation because its well-developed corporate law and capable judiciary make the resolution of legal issues predictable and efficient. In addition, Delaware is generally regarded as business-friendly, making it a great place for your start-up.

Fortunately, forming and organizing a Delaware corporation is an intuitive process.

Here is how it is done:

  1. Draft a Certificate of Incorporation – This is the “birth certificate” of your new entity and it contains general information about the corporation. Once filed with the Delaware Secretary of State, a Certificate of Incorporation can only be amended by the vote of the stockholders. Thus, it is common that an incorporator will include governing rules that it does not want the board of directors or minority stockholders to change easily (e.g., preemptive rights and jurisdiction and forum selection clauses). A Certificate of Incorporation is signed by the person who files it, who is known as the “incorporator.”
  2. Draft Bylaws – If a Certificate of Incorporation is the “birth certificate” of your corporation, the bylaws are its “constitution.” Bylaws will contain, among other things, voting procedures for the board and stockholders, annual meeting requirements, and provisions concerning officers. This document is not filed with the Delaware Secretary of State but should be kept with the corporation’s important documents.
  3. Prepare the Action of Incorporator – The incorporator should sign a document that is often called the “Organizational Action of the Incorporator.” This document can do a number of things but, most importantly, it identifies the first board of directors of the corporation and formally adopt the bylaws.
  4. Hold an Initial Meeting – Whether through an initial meeting or a consent of the board, the board will usually appoint officers, ratify the acts of the incorporator, and grant banking power to certain officers or directors. Most importantly, the corporation will also issue stock to the corporation’s first stockholders (also known as shareholders). The easiest way to do this is through an Initial Consent in Lieu of Organizational Meeting,” which is a document that sets forth the foregoing. To comply with Section 141(f) of the Delaware General Corporation Law, the unanimous written consent must be signed by each director. If the board cannot unanimously agree to the matters in the consent, it must hold a meeting and vote on each item. With respect to the issuance of stock, the secretary of the corporation generally issues stock certificates to the new stockholders following the initial meeting or after the consent is executed.

Additional documents are sometimes necessary or prudent. We often recommend that stockholders also enter into a stockholders (or shareholders) agreement that provides for management and stock transfer provisions that are not typically contained in a corporation’s bylaws.


Andrew Silverman is an attorney in the firm’s Business Department whose practice includes complex corporate governance and financing matters. If you are a Delaware business owner and desire guidance in forming a corporation, call (610) 840-0286 or email asilverman@macelree.com.
Filed Under: Articles by Our Attorneys Tagged With: Andrew Silverman, Business law

Stockholder Agreements in Delaware Corporations

July 26, 2019 by Andrew R. Silverman, Esq.

Stockholder-Agreements_MacElree-Harvey-Andrew-Silverman

By Andrew R. Silverman, Esquire-

A Delaware corporation is governed, first, by its Certificate of Incorporation and, second, by its bylaws. These agreements cover important but basic and default rules concerning governance of the corporation. A stockholders agreement (sometimes called shareholders agreement or, in the LLC context, a members agreement) contains more complex and, often, heavily negotiated provisions.

Typical issues covered in a stockholders agreement include:

  • Management and voting. In a stockholders agreement, stockholders can agree that they will vote for certain individuals as directors and officers. If the corporation is a party to the agreement, the stockholders may also agree to reserve certain business decisions to the stockholders rather than the board.
  • Restrictive Covenants. The stockholders may desire to bind each other to restrictive covenants that prevent the stockholders from competing against the company or soliciting the company’s clients during and after the stockholders’ ownership of stock in the company. The stockholders may also want to address confidentiality, trade secrets, and anti-disparagement in the stockholders agreement.
  • Transfer Provisions. The stockholders may desire to restrict the transfer of stock or to determine, in advance, how and when transfers may occur. For instance, a stockholders agreement may provide the stockholders options to purchase upon a stockholders’ death, divorce, disability, or bad conduct. A stockholders agreement is also where stockholders will find preemptive rights (if not in the Certificate of Incorporation), tag-along rights, rights of first refusal and first offer, drag-along rights, put and call rights, and change in control procedures.

Stockholders agreements are not required by the Delaware General Corporation Law, but they are advisable for some start-ups, closely-held or small corporations where the stockholders need to describe in detail the manner by which the corporation should be managed and how shares should be transferred, stockholders who desire anti-dilution provisions, and countless other scenarios.


Andrew Silverman is an attorney in the firm’s Business Department whose practice includes complex corporate governance and financing matters. If you are a Delaware business owner and desire guidance in establishing stockholder agreements, call (610) 840-0286 or email asilverman@macelree.com.
Filed Under: Articles by Our Attorneys Tagged With: Andrew Silverman, Business law

  • « Go to Previous Page
  • Page 1
  • Page 2

Primary Sidebar

Footer

(610) 436-0100

LEGAL SERVICES

ABOUT US

NEWS & INSIGHTS

OFFICES

Centreville, DE

5721 Kennett Pike
Wilmington, DE 19807
302-654-4454
Learn More

Kennett Square, PA

209 East State Street Road
Kennett Square, PA 19348
610-444-3180
Learn More

West Chester, PA

17 West Miner Street
West Chester, PA 19382
610-436-0100
Learn More

  • Terms of Use
  • Privacy Policy
  • Disclaimer
  • Staff Only
  • Careers

© 2026 and all rights reserved by MacElree Harvey, Ltd.