• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer
MacElree Harvey, Ltd.

MacElree Harvey, Ltd.

Initiative in Practice

  • Home
  • Legal Services
        • Banking & Finance Law
        • Business & Corporate Law
        • Criminal Defense
        • Employment Law
        • Estates & Trusts Law
        • Family Law
        • Litigation Law
        • Mediation and Arbitration
        • Personal Injury Law
        • Real Estate & Land Use Law
        • Tax Law
  • Our Team
        • Joseph A. Bellinghieri
        • Hiruy Y. Berhane
        • Patrick J. Boyer
        • Krzysztof M. Bozentka
        • Jeffrey P. Burke
        • Robert A. Burke
        • Matthew C. Cooper
        • Marie I. Crossley
        • Pilar Diaz
        • Harry J. DiDonato
        • Jaycie DiNardo
        • Caroline G. Donato
        • Nicholas S. Eisel
        • Sally A. Farrell
        • Brian J. Forgue
        • William J. Gallagher
        • Patrick J. Gallo, Jr.
        • Mary Kay Gaver
        • J. Charles Gerbron, Jr.
        • Leo M. Gibbons
        • Joseph P. Green, Jr.
        • Frank W. Hosking III
        • Katherine A. Isard
        • Peter E. Kratsa
        • Mary E. Lawrence
        • Daniel R. Losco
        • Michael G. Louis
        • John F. McKenna
        • Matthew M. McKeon
        • Lou Mincarelli
        • Brian L. Nagle
        • Lance J. Nelson
        • Timothy F. Rayne
        • Michael C. Rovito
        • Duke Schneider
        • Andrew R. Silverman
        • Ashley B. Stitzer
        • Patrick L. Ware
        • Jeremy A. Whalen
        • Natalie R. Young
  • About Us
    • Our History
    • Our Approach
    • Social Responsibility
    • Testimonials
  • Careers
  • News & Updates
    • Articles by Our Attorneys
    • News
    • Podcasts
    • Videos
    • Newsletters
  • Offices
    • Centreville, DE
    • Kennett Square, PA
    • West Chester, PA
  • Contact
  • (610) 436-0100

Andrew Silverman

Connelly v. United States: Why Business Owners Should Revisit Their Buy-Sell Agreements

September 23, 2026 by Andrew R. Silverman, Esq. Leave a Comment

What the Supreme Court’s decision means for life insurance-funded buy-sell agreements.

By Andrew R. Silverman

If you own a closely held business, chances are you signed a buy-sell agreement years ago and have not looked at it since. Many of those agreements rely on life insurance to fund the purchase of an owner’s interest following death.

Until recently, business owners and their advisers generally assumed that this arrangement would not increase the estate tax value of the business. The United States Supreme Court’s 2024 decision in Connelly v. United States calls that assumption into question.

For owners whose companies use life insurance to fund a company’s buy-back of a deceased owner’s interest (also known as a redemption), the practical issue is straightforward: Does the buy-sell agreement still operate the way the owners intended? For many businesses, the answer may be no.

How Life Insurance-Funded Buy-Sell Agreements Work

A buy-sell agreement establishes what happens to an owner’s interest when that owner dies, becomes disabled, retires, or experiences another specified event. Upon an owner’s death, the agreement typically requires either the company or the surviving owners to purchase the deceased owner’s interest.

Many buy-sell agreements use life insurance to fund that purchase.

One of the most common arrangements is a redemption agreement. Under this structure, the company owns a life insurance policy on each owner. When an owner dies, the company receives the insurance proceeds and uses them to purchase, or redeem, the deceased owner’s shares from the estate.

The arrangement is popular because it is relatively easy to administer. The company pays the premiums, owns the policies, and handles the buyout. The surviving owners do not have to fund the purchase personally at a difficult time.

The structure historically rested on a seemingly logical assumption. Although the insurance proceeds increase the company’s assets, the company also has an obligation to use those proceeds to redeem the deceased owner’s shares. If the incoming insurance proceeds and outgoing redemption payment offset one another, the insurance should not increase the value of the company or the deceased owner’s interest for estate tax purposes.

In Connelly, the Supreme Court unanimously rejected that assumption under the facts before it.

What Connelly Means for Redemption Buy-Sell Agreements

Connelly v. United States, 602 U.S. 257 (2024), involved two brothers who owned a Missouri building-supply company. Their company had a buy-sell agreement designed to provide for the purchase of an owner’s shares following death.

When one brother, Michael Connelly, died, the company received $3.5 million in life insurance proceeds. It used $3 million to redeem Michael’s shares. His estate valued the company at approximately $3.86 million without including the insurance proceeds.

The IRS took a different position. It included the proceeds and valued the company at $6.86 million. The Supreme Court agreed with the IRS.

The Court reasoned that a redemption at fair market value does not reduce the company’s value in the same way as an ordinary debt. A company with $10 million in assets and an obligation to redeem $3 million of its shares remains worth $10 million immediately before the redemption. After the company pays $3 million and redeems the shares, the remaining shareholders collectively own a company worth $7 million, but they own a larger percentage of it. Their economic position has not been reduced by the redemption obligation.

The life insurance proceeds, by contrast, are an asset of the company and increase its value. The obligation to redeem the deceased owner’s shares generally does not offset that increase.

The result is that company-owned life insurance may increase the value of the very shares the insurance was intended to purchase. The estate may therefore owe tax based on value that it does not ultimately retain.

Consider a company worth $10 million before taking its insurance into account. If the company receives $5 million in death benefits, its value for estate tax purposes may increase to $15 million immediately before the redemption. The deceased owner’s shares are valued using that higher company value, even though the insurance proceeds will be used to purchase those shares.

The Connelly Holding Has Limits

The decision should not be read more broadly than necessary.

The Supreme Court did not hold that a redemption obligation can never affect the value of a company. It left open the possibility that a redemption obligation could reduce value when satisfying it would impair the company’s operations or future earning capacity. For example, the analysis may be different if a company must sell operating assets, incur substantial debt, or otherwise damage its business to complete the redemption.

That was not the situation in Connelly. The company held life insurance specifically intended to fund the purchase. Because the insurance proceeds were available to satisfy the redemption obligation, the payment did not impair the company’s underlying operations.

Most conventional insurance-funded redemption agreements are likely to present the same basic concern. The company owns the policy, receives the proceeds, and uses those proceeds to purchase the deceased owner’s interest. Those arrangements fall within the central reasoning of Connelly.

Why Higher Estate Tax Exemptions Do Not Eliminate the Risk

The federal estate and gift tax exclusion increased to $15 million per person effective January 1, 2026, subject to inflation adjustments. A married couple may be able to shelter $30 million through proper planning, and many estates will not owe federal estate tax.

That does not mean business owners should ignore Connelly.

First, the decision can increase the value being measured. A business worth $9 million, with $6 million of company-owned life insurance, may be treated as a $15 million business upon an owner’s death. The valuation occurs at death, potentially after years of growth and appreciation. Today’s business value may not reflect the value that will be included in an owner’s estate years from now.

Second, the current exclusion has no scheduled expiration, but Congress can change federal tax law. An owner’s estate tax exposure will depend on the law and the value of the business at the time of death, not when the buy-sell agreement was signed or last reviewed.

Third, the choice between a redemption and a cross-purchase arrangement affects more than estate tax. The structure may determine whether surviving owners receive additional tax basis in the acquired interest. It also affects whether the life insurance proceeds are exposed to claims by the company’s creditors.

Pennsylvania business owners should also remember that the Commonwealth’s inheritance tax operates independently of the federal estate tax system. Even when no federal estate tax is due, state-level transfer tax considerations may remain relevant.

The larger federal exclusion reduces the number of estates immediately affected by Connelly, but it does not make the design of the buy-sell agreement irrelevant.

Can the Price in a Buy-Sell Agreement Control Estate Tax Value?

Many owners assume that the price stated in their buy-sell agreement determines the value of the business for estate tax purposes. A well-drafted pricing provision can help prevent disputes among the surviving owners and the deceased owner’s estate. It does not automatically bind the IRS.

Internal Revenue Code § 2703 generally directs the IRS to disregard an agreement that permits property to be acquired for less than fair market value unless the agreement satisfies several requirements. Among other things, the arrangement must serve a bona fide business purpose, cannot operate as a device to transfer property to family members for less than full and adequate consideration, and must contain terms comparable to those found in an arm’s-length transaction.

Courts apply these requirements carefully, particularly when the owners are related.

The agreement in Connelly did not contain a binding fixed or formula price. It contemplated that the brothers would agree on a value each year. They never did. The agreement provided an appraisal process if the parties did not agree, but that process was not  followed before the company and the estate negotiated the redemption price.

Better pricing discipline might have reduced uncertainty between the company and the estate. It would not necessarily have changed the treatment of the company-owned life insurance proceeds.

A defensible valuation provision remains an important part of a buy-sell agreement, but it does not, by itself, remove company-owned insurance from the company’s value.

Planning Options After Connelly

There is no single replacement structure that works for every business. The appropriate response depends on the number of owners, the company’s entity and tax classification, the owners’ estate plans, the value and terms of existing policies, and the company’s ability to fund future premiums.

The principal planning options include the following.

Cross-Purchase Agreement

Under a cross-purchase agreement, the individual owners, rather than the company, own life insurance policies on one another. When an owner dies, the surviving owners receive the insurance proceeds and use them to purchase the deceased owner’s interest directly.

Because the insurance proceeds do not enter the company, they do not increase the company’s value. The purchasing owners also generally receive tax basis in the interest they acquire, which may reduce their taxable gain on a later sale.

The disadvantages are practical. Each owner must fund premiums personally. If the company has several owners, the number of required policies can multiply quickly. Changes in ownership may also require corresponding changes to the insurance structure.

Insurance LLC

An insurance LLC may address some of the administrative problems associated with a traditional cross-purchase arrangement. Under this structure, a separate limited liability company, ordinarily taxed as a partnership, owns and administers one life insurance policy for each business owner.

Centralized ownership can reduce the number of policies and simplify premium administration. If properly structured, the arrangement may also qualify for the partnership exception to the transfer-for-value rule under Internal Revenue Code § 101(a)(2)(B).

An insurance LLC is not a plug-and-play solution. Its estate tax treatment relies in part on IRS guidance rather than a definitive judicial framework. The LLC must be respected as a genuine partnership, and the governing documents, economic arrangements, insurance policies, and transfer provisions must work together. This option requires careful design and ongoing administration.

Additional Life Insurance

Owners who want to retain a redemption structure may purchase additional insurance intended to cover both the redemption price and the resulting estate tax exposure.

The approach can work mathematically, but it has limitations. Additional coverage means additional premiums, and the appropriate amount must be reevaluated as the business grows. The proceeds remain company assets and may remain exposed to the company’s creditors. Additional insurance may fund the tax created by the structure without addressing the underlying valuation issue.

Trust Ownership

In appropriate circumstances, an irrevocable life insurance trust may own a policy on a business owner’s life. If properly structured and administered, the proceeds may remain outside both the company and the insured owner’s taxable estate.

Execution is critical. The trust generally must own the policy, not simply be named as its beneficiary. Transferring an existing policy can also create estate tax timing issues and implicate the transfer-for-value rules. A trust-owned policy must be coordinated with the buy-sell agreement, the owner’s estate plan, and the source of premium payments.

Practical Tip: Verify the Insurance Records First

Before changing a buy-sell agreement or moving any policy, confirm:

  • Who owns each life insurance policy.
  • Who is named as the beneficiary.
  • Who pays the premiums.
  • Whether any policy has been transferred.
  • Whether the coverage remains sufficient in light of the company’s current value.
  • Whether the policy terms and designations match the buy-sell agreement.

Insurance paperwork often does not match the owners’ understanding of how the arrangement is supposed to work. A change in ownership, beneficiary designation, or premium arrangement may also have tax consequences. Moving an existing policy can raise issues that would not arise if the parties purchased a new policy.

The policy records and the agreement should therefore be reviewed together.

When Should Business Owners Review Their Buy-Sell Agreements?

A review following Connelly does not need to become an open-ended business succession planning exercise. It should begin with a focused examination of:

  • The structure of the existing buy-sell agreement.
  • The ownership and beneficiary designations for each life insurance policy.
  • The agreement’s valuation and pricing provisions.
  • Compliance with Internal Revenue Code § 2703.
  • The company’s entity and tax classification.
  • The income tax basis consequences to the surviving owners.
  • The potential exposure of insurance proceeds to company creditors.
  • The relationship between the buy-sell agreement and each owner’s estate plan.

For some businesses, the existing redemption structure may remain appropriate. For others, a cross-purchase agreement, insurance LLC, trust-owned policy, or another modification may better accomplish the owners’ objectives.

Business owners should consider a review if their agreement has not been examined since Connelly, particularly where the business has experienced significant growth, an owner’s health has changed, the company is preparing for a transaction, or the ownership group expects to change.

The most important step is to understand how the agreement and insurance policies work before an owner dies. A buy-sell agreement should provide certainty at a difficult time. It should not create an estate tax result that the owners never intended.
Filed Under: Articles by Our Attorneys Tagged With: Andrew Silverman

Independent Practice Authority for Delaware Physician Associates 

August 4, 2026 by Andrew R. Silverman, Esq. Leave a Comment

This article is part of a series on Delaware’s new Physician Associate Act. Start with Delaware’s New Physician Associate Act: What Changed and Who It Affects. 

A physician associate who has practiced in Delaware for several years and is considering what comes next now has an option that did not exist a year ago. House Bill 325, signed May 12, 2026, permits a physician associate with sufficient clinical experience to seek authority to practice without a collaborating physician. 

The question that follows is a practical one: who qualifies, how does the application work, and what does the authority actually change? The threshold is specific, the application runs through a body most physician associates have never dealt with, and the authority does somewhat less than the coverage of the new law suggests. 

Collaboration remains the default 

Except in a medical emergency or as otherwise provided, a physician associate may not perform any medical act without a collaborative agreement, and nothing in the chapter authorizes a physician associate with fewer than 6,000 post-graduate clinical hours to practice independent of a collaborating physician. (24 Del. C. § 1772.) 

There are exactly three exceptions. 

  1. Independent practice authority, discussed below. We refer to it throughout as “independent practice authority” or “IPA.” 
  1. Uncompensated volunteer or charitable care, which may be rendered without a collaborating physician, or with such collaborating physicians as are available. (24 Del. C. § 1774E.) 
  1. A medical emergency. 

That is the complete list. Seniority alone does not qualify a physician associate to practice independently, and neither does an employer’s willingness to operate without oversight. 

What independent practice authority requires 

More than 6,000 post-graduate clinical practice hours. Below that threshold, independent practice is expressly unauthorized and there is no discretionary waiver. For a physician associate practicing full time, the threshold generally arrives somewhere around the three-to-four-year mark, although part-time and intermittent practice will extend that considerably. 

An application to the Regulatory Council for Physician Associates. A qualifying physician associate who intends to practice without a collaborative agreement must apply, and the Council verifies the hours. 

One of two application tracks. Which track applies matters more than it initially appears. 

  1. Practice in a setting with at least one licensed Delaware physician in the group, practice, or health system. 
  1. Practice in a setting without such a physician. This track additionally requires proof that the physician associate has had training which aligns to the physician associate’s practice areas. 

Both forms require the physician associate’s name, license number, practice location, contact information, primary practice area, and proof of the required hours. In addition, a physician associate who later changes practice areas must notify the Council beforehand, again with proof of aligned training. 

The second track is the one that matters for a physician associate planning a solo practice or a practice without a physician in the group, and it carries the additional documentary burden. 

When applications can be filed 

House Bill 325 was signed on May 12, 2026. Although the Act carries a May 12, 2026 effective date, the new independent-practice framework is not fully operational until the earlier of Board approval of implementing regulations or May 12, 2027. 

Those regulations have not been adopted as of the date of this article. Thus, the application forms described in the statute do not yet exist in usable form and no physician associate can presently file. The outside date is May 12, 2027, though the regulations may issue sooner. 

What independent practice authority does not do 

  • It does not end the duty to consult and refer. Every physician associate, whether or not he or she holds independent practice authority, must collaborate with, consult with, and refer to the appropriate member of the healthcare team as indicated by the patient’s condition and by the physician associate’s own education, experience, and competencies. Independent practice authority removes the collaborative agreement; it does not remove the underlying obligation of clinical judgment, and it does not alter the standard of care. 
  • It does not displace the license. A physician associate’s authority flows entirely from the Chapter 17 license. Treating a Delaware patient constitutes practice “in this State,” and unlicensed practice as a physician associate is a criminal offense carrying a fine of $500 to $2,000, imprisonment of up to one year, or both. (24 Del. C. § 1774B.) This is most easily overlooked by physician associates practicing remotely, who may assume that their physical location governs. It does not. 
  • It does not by itself authorize a physician associate to own or operate a practice. Ownership of a practice entity and authority to practice independently are related but distinct questions, and Section 1772 contains a provision concerning the maintenance or management of a practice location that reaches physician associates who have not obtained independent practice authority. A physician associate planning to practice through his or her own limited liability company should review that provision before forming anything, and we address it in detail in the telehealth and entity structure article. 

A note for physician associates re-entering practice 

A physician associate returning after more than three years away from practice, including one who was practicing in another United States jurisdiction, may be subject to Board-imposed re-entry conditions. Those conditions may include requiring the collaborating physician to be physically on site while the physician associate is practicing. (24 Del. C. § 1774D.) 

An on-site requirement will foreclose remote practice for as long as it remains in force. A physician associate planning a telehealth practice after time away from Delaware should therefore resolve this question before building a practice model around remote delivery. 

What can be done while the regulations are pending 

Although no application can be filed today, the preparatory work is entirely documentary and can begin immediately. 

  1. Assemble documentation of clinical hours. Verification is the Council’s responsibility, but assembly is the applicant’s, and reconstructing several years of clinical hours after the fact is considerably more difficult than exporting the records while system access to a current or former employer remains available. Physician associates who have changed positions more than once should begin here. 
  1. Map training records to intended practice areas. For a physician associate who plans to practice in a setting with no Delaware physician in the group, the aligned-training requirement is, on the statutory language, the item most likely to delay an application. Continuing education certificates, specialty training records, and procedure logs are all more easily gathered now than under a filing deadline. 
  1. Consider the practice area designation carefully. Because a later change in practice areas requires advance notice to the Council together with fresh proof of aligned training, the designation on the initial application is not a formality. 

TIP: If a change in employment is contemplated in the next year, gather the hour documentation before giving notice. Former employers are generally cooperative, but requests made after a departure move more slowly than requests made before one. 

Conclusion 

The qualifying threshold is hours, the gatekeeper is the Regulatory Council, and the preparation is documentary, which means it can be substantially completed before the application process opens. 

Physician associates considering independent practice, and particularly those contemplating a practice with no physician in the group, are advised to review both their documentation and their intended practice structure with counsel before the regulations issue, because the entity and licensure questions are more closely connected than they first appear. 

Also in this series: [Telehealth, Limited Liability Companies, and Independent Practice] and, for employers, [how the four-physician-associate collaboration cap works]. 


Andy Silverman is a partner in the Business Department at MacElree Harvey, Ltd. He advises medical practices and providers on business structure and governance, equity and physician compensation arrangements, employment agreements, private equity and M&A transactions, and regulatory and tax matters. Admitted in both Delaware and Pennsylvania, he holds an LL.M. in Taxation from Villanova University School of Law and is a member of the American Health Law Association. 

This article reflects Delaware law as of August 4, 2026. The Regulatory Council’s implementing regulations had not been adopted as of publication. 

This article is for general informational purposes and does not constitute legal advice or create an attorney-client relationship. Attorney advertising. 

Filed Under: Articles by Our Attorneys Tagged With: Andrew R. Silverman, Andrew Silverman

Telehealth, Limited Liability Companies, and Independent Practice: A Structural Guide for Delaware Physician Associates 

August 4, 2026 by Andrew R. Silverman, Esq. Leave a Comment

This article is part of a series on Delaware’s new Physician Associate Act. Start with Delaware’s New Physician Associate Act: What Changed and Who It Affects. 

A growing number of physician associates deliver care remotely through an entity they own, contracting with a collaborating physician rather than working as that physician’s employee. It is an efficient structure, and Delaware’s House Bill 325, signed May 12, 2026, changes what it can look like. 

Three questions drive the analysis. Does the collaboration cap follow a physician associate into telehealth? What does Delaware’s general telehealth statute require on top of the Physician Associate Act? And may a physician associate actually own the entity through which he or she practices? 

The short answers are yes, a good deal, and probably. The details are where the structuring occurs. 

Telehealth is within scope, and collaboration may be electronic 

The Act lists among a physician associate’s authorized medical acts the use of telemedicine and the use of and participation in telehealth, and a physician associate may be designated a primary care provider by an insurer. (24 Del. C. § 1773.) 

The collaboration rules were drafted to work remotely. Constant physical presence of the collaborating physician is not required on site, provided that the collaborating physician is readily accessible by some form of electronic communication. (24 Del. C. § 1770A.) Where the physician is not routinely present, adequate means and methods may include telecommunication, chart review, or other methods of communication and oversight. (24 Del. C. § 1771.) 

One limitation survives all of this. The collaborating physician may not be involved in patient care in name only and must be involved in active patient care on a regular basis. A collaborating physician who signs an agreement, collects a monthly fee, and never opens a chart is therefore not a compliance structure; that arrangement places the physician’s license at risk and, by extension, the continuity of the practice that depends on it. 

The cap applies to remote practice, but its exception does not 

The four-physician-associate concurrent cap applies to remote practice unchanged. A collaborating physician may not collaborate with more than four physician associates at any given time. (24 Del. C. § 1771.) 

The cap’s exception, however, is tied to physicians and physician associates practicing in the same “physical office or facility building,” and a distributed remote arrangement across multiple locations does not satisfy that language. 

The result is somewhat counterintuitive. A telehealth practice has fewer compliance options than a brick-and-mortar practice, not more, because the exception most readily available to a physical clinic is simply unavailable to it. What remains is scheduling discipline, the addition of collaborating physicians, the use of physician associates holding independent practice authority, and an application to the Board for an exemption. 

Telehealth rules apply in addition to the Physician Associate Act 

Because physician associates are licensed by the Board of Medical Licensure and Discipline, they are authorized to deliver telehealth subject to the provisions of Delaware’s general telehealth statute. (24 Del. C. ch. 60.) That chapter imposes requirements entirely independent of the collaboration rules. 

  • A provider-patient relationship, which may be established in person or by telehealth, including verification of the patient’s location, disclosure of the provider’s identity and credentials, informed consent, a diagnosis by acceptable medical practices, a discussion of options, follow-up coverage, and a written visit summary. (§ 6003.) 
  • The same standard of care as in-person treatment. Treatment is held to in-person standards, and prescribing based solely upon an internet questionnaire or consultation is prohibited. (§ 6003.) 
  • An approved modality before diagnosis or treatment, meaning an in-person examination, another Delaware-licensed provider present at the originating site, diagnosis by audio or visual communication, or compliance with professional-society telemedicine guidelines, together with complete recordkeeping. (§ 6004.) 

The statutory definitions of “telehealth” and “telemedicine” are broad, reaching real-time two-way audio-visual communication, audio-only communication where broadband is unavailable, and store-and-forward transfer. That last category is worth noting for image-based specialties such as dermatology, where the asynchronous workflow is generally the practice model rather than a fallback. 

The patient’s location governs, not the provider’s 

This point is frequently misunderstood and it is worth stating directly. Delaware keys telehealth authorization to the Delaware license and to the patient’s location and not to where the provider happens to be. 

The statutory definitions confirm it. An “originating site,” meaning the patient’s location, “means a site in Delaware.” A “distant site,” meaning the provider’s location, “means a site at which a health-care provider legally allowed to practice in Delaware is located,” and carries no Delaware-location requirement. (24 Del. C. § 6001.) The operative trigger is verification of the patient’s location. 

Two consequences follow. 

  1. Delaware’s interstate telehealth registration is not the pathway for a Delaware-licensed physician associate. That registration exists for providers licensed in a state that has not adopted an interstate compact and who are not otherwise licensed in Delaware. A physician associate who already holds a Delaware license practices under the license authorization instead. 
  1. Delaware law does not resolve the requirements of the provider’s home state. Chapter 60 governs the Delaware side only. It does not require a physician associate to be licensed where he or she physically sits, and it does not speak to that state’s law. Whether the state in which the provider is located independently regulates practice originating there is a separate, state-by-state question that Delaware law does not answer, and it should be cleared for every provider in every state from which that provider works. In our experience, this is the most common gap in otherwise well-constructed remote practices. 

May a physician associate own the practice entity? 

For a physician associate forming a limited liability company and contracting with a collaborating physician, this is the threshold question. The answer is a qualified yes, subject to one significant limitation and several open items. 

Entity eligibility is not the obstacle 

The statute defines a physician associate as an individual who “is licensed under this chapter to practice medicine as a physician associate.” (24 Del. C. § 1770A.) That satisfies the predicate in Delaware’s Professional Service Corporation Act, which extends eligibility to persons “duly licensed or otherwise legally authorized to render the same professional service.” (8 Del. C. §§ 603, 605.) Because the Act’s test is licensure or other legal authorization to render the service, rather than possession of a full physician’s certificate, a physician associate qualifies. 

Delaware does not mandate a professional entity and has no professional LLC statute 

The professional corporation regime is an optional overlay rather than the exclusive path, and Delaware has no separate professional limited liability company act. Professional services may accordingly be delivered through an ordinary limited liability company formed under the general Limited Liability Company Act. (6 Del. C. ch. 18.) 

Physician associates coming from states that have a professional limited liability company form are often misled by the terminology. In Delaware, professional restrictions on ownership and transfer are written into the operating agreement by contract rather than supplied by the entity form itself. That is more flexible, but it also means that nothing protects the owners by default. 

If a professional corporation is used, all owners must render the same professional service 

Where a physician associate elects the professional corporation form, the same-profession ownership limitation applies. Every shareholder must be an individual duly licensed or otherwise legally authorized to render the same professional service, and the only multi-profession combination the Act permits is the practice of medicine together with the practice of podiatry. (8 Del. C. §§ 603, 610.) 

The consequence is direct. A physician associate and a collaborating physician cannot co-own a Delaware medical professional corporation. For any arrangement contemplating shared equity between a physician associate and the collaborating physician, that limitation alone generally settles the entity choice in favor of the limited liability company. 

The limitation to watch 

Under 24 Del. C. § 1772(a), a physician associate “may not maintain or manage a location that does not have oversight by the physician associate’s collaborating physician.” 

Read against a physician-associate-owned practice entity, the implication is immediate. A physician associate who owns the limited liability company but does not hold independent practice authority must have collaborating-physician oversight of that location. House Bill 325 did not repeal the provision; it carved out around it, exempting a physician associate granted independent practice authority from the section entirely. (24 Del. C. § 1772(i).) 

For that reason, entity ownership and independent practice authority are not separate questions. For a physician-associate-owned practice, independent practice authority is not merely a convenience that eliminates a collaborative agreement. It is what removes the maintain-or-manage limitation on the practice location itself, and the two should be sequenced accordingly. 

TIP: Where the 6,000-hour threshold is still some distance away, the practical structure is generally to form the entity now and to build genuine collaborating-physician oversight of the location into the collaboration agreement, rather than to defer formation. The entity can then continue unchanged once independent practice authority issues. 

Ownership is not authority 

Finally, and importantly, owning the entity does not authorize independent practice. The collaboration requirement runs to a physician associate’s clinical acts rather than to the ownership of the practice. A physician associate who forms an entity while still short of the 6,000-hour threshold has organized a business, not expanded a license. 

Open items to consider before committing capital 

Several questions in this area remain genuinely unresolved, and a physician associate building a practice around this structure should understand them at the outset. 

  • Corporate practice of medicine. Delaware has no clear position. No statute, reported decision, Board regulation, or Attorney General opinion squarely addresses whether an entity may employ physicians or physician associates to render medical services. The conclusion above therefore rests substantially on the absence of a prohibition rather than on affirmative authority, which is a materially weaker foundation even if it is the correct reading. (At least one commercial source in circulation asserts that Delaware enforces corporate practice restrictions through the Professional Service Corporation Act. That appears to be an over-reading, since the chapter binds only those entities that elect to organize under it.) 
  • Payor credentialing. Whether commercial payors will credential a physician-associate-owned entity in Delaware is not documented. The statute now provides that physician associates must be authorized to bill for and receive direct payment for the medically necessary services they deliver, and that no insurance company or third-party payer may impose a practice, education, or collaboration requirement inconsistent with or more restrictive than state law. Whether payor operations have caught up to those provisions is a separate question, and a statute only months old has likely not yet resolved it in practice. 
  • Delaware Medicaid. Published Delaware Medicaid materials appear to condition billing for physician associate services on the individual being in an enrolled practitioner’s or enrolled group’s employ, and those materials predate House Bill 325. The current posture should be confirmed with the Division of Medicaid and Medical Assistance directly rather than taken from the published manual. For a physician-associate-owned entity with meaningful Medicaid volume, this is a threshold question of viability rather than a detail. 
  • Federal law operates independently. Compensation flowing from a physician-associate-owned entity to a collaborating physician implicates the federal Anti-Kickback Statute and its personal services safe harbor, and where that physician also refers into the entity, the Stark Law is implicated as well. None of this was affected by House Bill 325, and all of it can defeat an arrangement that is entirely lawful as a matter of Delaware entity law. 

Conclusion 

A Delaware physician associate may very likely own the entity through which he or she practices, and a limited liability company formed under the general Limited Liability Company Act is ordinarily the appropriate form rather than a professional corporation. Independent practice authority is what removes the limitation on maintaining or managing the practice location, and it should therefore be sequenced ahead of the entity build rather than treated as a later upgrade. The four-physician-associate cap follows the practice into telehealth without the same-building exception that assists physical clinics. And the unresolved risk in this structure sits in payor credentialing and federal compensation analysis rather than in Delaware entity law. 

For a physician associate building this kind of practice, the order of operations matters at least as much as the entity documents. We generally recommend confirming the hours, identifying the applicable application track, testing payor credentialing early, and structuring the collaborating physician’s compensation against the federal safe harbors before any agreement is signed. 

Also in this series: [the overview], [how the four-physician-associate collaboration cap works](#), and [independent practice authority eligibility and application]. 

Andy Silverman is a partner in the Business Department at MacElree Harvey, Ltd. He advises medical practices and providers on business structure and governance, equity and physician compensation arrangements, employment agreements, private equity and M&A transactions, and regulatory and tax matters. Admitted in both Delaware and Pennsylvania, he holds an LL.M. in Taxation from Villanova University School of Law and is a member of the American Health Law Association. 

This article reflects Delaware law as of August 4, 2026. The Regulatory Council’s implementing regulations had not been adopted as of publication. 

This article is for general informational purposes and does not constitute legal advice or create an attorney-client relationship. Attorney advertising.

Filed Under: Articles by Our Attorneys Tagged With: Andrew R. Silverman, Andrew Silverman

Want to Sell Your Business? Start Now. 

June 9, 2026 by Andrew R. Silverman, Esq. Leave a Comment

Author: Andrew R. Silverman, Business Attorney at MacElree Harvey, Ltd.

Imagine staring into your computer as a grid of unfamiliar faces—lawyers, accountants, and private equity professionals—fires questions at you about every corner of your business: financials, taxes, contracts, leases, customers, suppliers, employees, ownership, intellectual property, equipment, inventory, A/R, A/P, and more. The questions keep coming, rapid and relentless, and for hours you are expected to have clear, consistent answers. Would you? 

The reality is that the more prepared you are when that moment arrives, the easier and more successful the process will be. Buyers–whether private equity firms or SBA-backed individuals– are looking for businesses they can understand, trust, and step into with confidence. These buyers are willing to pay more for that certainty. The best outcomes do not come from scrambling after a letter of intent is signed. They are the result of years of consistent financial reporting, clean corporate hygiene, documented relationships, and disciplined planning. 

What You Can Do Right Now 

Regardless of timing, owners can immediately improve exit readiness by reducing legal, financial, and operational ambiguity. 

  • Document all related party arrangements, including leases and loans to owners 
  • Get financials clean, consistent, and explainable 
  • Confirm ownership and equity structure is clear and documented 
  • Ensure all material contracts are signed and accessible 
  • Eliminate “handshake” arrangements—reduce all agreements to writing 
  • Centralize key documents (basic data room: organizational documents, tax filings, financials, employment agreements, IP, and contracts) 
  • Reduce reliance on any single person, customer, or vendor 

Ask yourself: if you had to explain your business to a buyer tomorrow, what would be unclear—or undocumented? 

Startup Phase: Build for Transferability 

At formation, most owners are focused on getting a product or service into the market. While exit may not be top of mind, the decisions made at this stage will shape both how the business operates—and how easy it is to sell later. 

  • Establish a clean legal structure—be deliberate about entity type, tax treatment, and cash flow 
  • Ensure all intellectual property is clearly owned by the company, including through written assignments from employees and contractors 
  • Avoid commingling and informal practices from the outset 
  • Document all key relationships (employees, customers, vendors) 
  • Require baseline protections (confidentiality and IP assignment agreements) 
  • Establish financial discipline early 
  • Build a trusted advisory team (accountant, banker, and legal counsel) 

You are not just building a business—you are building an asset someone else must be able to step into. 

Five Years from Sale: Institutionalize the Business 

At this stage, the business is established and performing. The focus shifts from growth to making the business legible—and credible—to a third party. Buyers are evaluating not just what the business can do, but how reliably it can continue to do it without you. 

  • Develop management depth beyond the founder 
  • Improve financial credibility—establish reviewed or audited financial statements and document any deviations or non-standard practices 
  • Identify, resolve, and document any issues in the financials that require explanation (e.g., unusual accounting treatments, slow A/P, inconsistent margins) 
  • Clean up legacy contracts and unresolved issues 
  • Address customer concentration risk where possible 
  • Evaluate tax and entity structure with a view toward an eventual exit and clarity to the buyer 

Buyers rarely expect perfection—but they quickly lose confidence where things are unclear. 

One Year from Sale: De-Risk the Transaction 

At this stage, the goal is to eliminate surprises. Buyers often lose confidence not because of performance, but because of what they find once diligence begins. If you identify and resolve those issues in advance, you control the narrative—and reduce the risk of late-stage disruption. 

  • Conduct a mock diligence review—what will a buyer find when it reviews your business and its documents? Find those issues now—before the buyer does 
  • Organize contracts, financials, and corporate records into a clear, accessible structure 
  • Clean up working capital and unusual balance sheet items (common sources of price adjustments) 
  • Resolve disputes, contingent liabilities, and informal arrangements before they surface in diligence 

At this stage, you are not increasing value—you are protecting it. 

Six Months from Sale: Optimize for Execution 

As a sale process begins, the focus becomes execution: speed, clarity, and credibility. At this point, preparation is visible—and it directly impacts how smoothly the process runs and how confident buyers feel. 

  • Prepare a fully organized, diligence-ready data room 
  • Ensure financial performance and the business narrative are consistent and explainable 
  • Identify and resolve third-party consents and approvals in advance 
  • Anticipate and prepare for key negotiation points (price adjustments, indemnification, etc.) 
  • Maintain steady performance—buyers closely monitor any changes during the process 

Deals rarely fail late because of price—they fail because of uncertainty or loss of confidence. 

Closing Thought 

The best exits are not engineered at the end—they are revealed over time. The sale process effectively begins long before you decide to sell—often before the business is even formed. The earlier you approach your business with that reality in mind, the more control you will have over the outcome when the time comes. 

Andrew R. Silverman is a business attorney at MacElree Harvey, Ltd., where he represents clients in a wide range of corporate and commercial matters. His practice includes business formation, governance, contracts, mergers and acquisitions, succession planning, and general counsel services for businesses of all sizes. Andrew works closely with business owners and executives to provide practical, strategic legal guidance tailored to their goals.

Filed Under: Articles by Our Attorneys Tagged With: Andrew R. Silverman, Andrew Silverman

15 MacElree Harvey Attorneys Named to Prestigious 2020 Super Lawyers/Rising Stars List

June 1, 2020 by MacElree Harvey, Ltd.

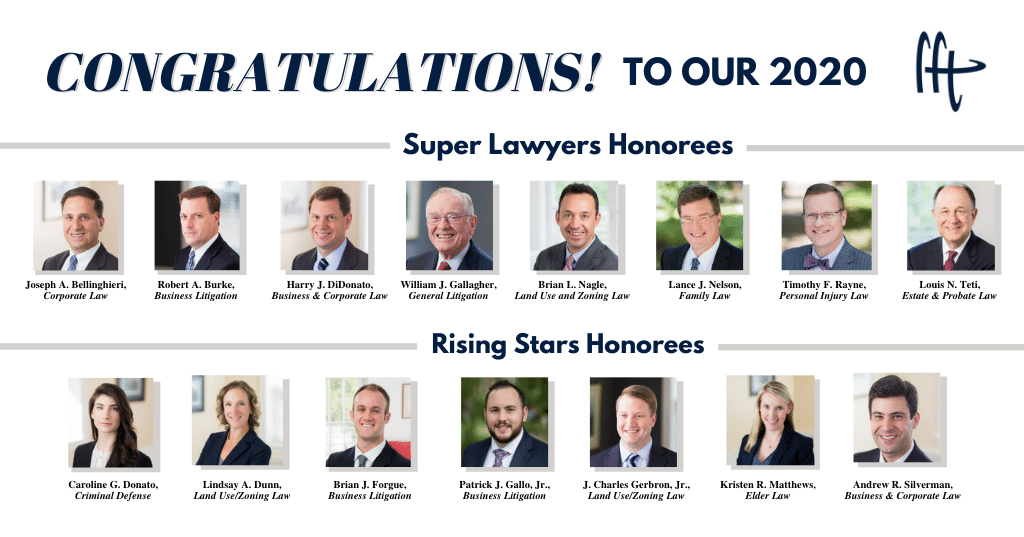
MacElree Harvey is pleased to announce the selection of 15 of its Pennsylvania attorneys to the prestigious list of Pennsylvania Super Lawyers or Rising Stars.

Super Lawyers is a rating service of outstanding lawyers operated by legal publisher Thompson Reuters which rates attorneys in more than 70 practice areas who attain a high degree of peer recognition and professional achievement.

Super Lawyers uses a patented multi-faceted selection process involving peer nominations, independent research regarding 12 indicators of professional achievement, peer evaluation by a Blue Ribbon Panel, and final selection.

Attorneys under age 40 or practicing less than 10 years are eligible for designation as Rising Stars and only 2.5 percent of eligible attorneys are selected.  In 2020, MacElree Harvey’s rising stars were:

  • Caroline Donato – Criminal Law
  • Lindsay Dunn – Land Use/Zoning
  • Brian Forgue – Business Litigation
  • Patrick Gallo – Business Litigation
  • Charles Gerbron – Land Use/Zoning
  • Kristen Matthews – Elder Law
  • Andrew Silverman – Business/Corporate Law

The Super Lawyers list is limited to only 5 percent of the eligible attorneys. MacElree Harvey’s 2020 Pennsylvania Super Lawyers were:

  • Joseph Bellinghieri – Estate and Probate
  • Robert Burke – Business Litigation
  • Harry DiDonato – Business/Corporate Law
  • William Gallagher – General Litigation
  • Brian Nagle –  Land Use/Zoning
  • Lance Nelson – Family Law
  • Tim Rayne – Personal Injury
  • Louis Teti – Estate and Probate

Harry DiDonato and Lance Nelson earned special designations in 2020 because they have been named as Super Lawyers for the last 10 years.

Tim Rayne was named as a Top 100 Super Lawyer in Pennsylvania.

“The firm is honored and humbled to have more of our attorneys named to the 2020 Super Lawyer/Rising Star list than any other Chester county-based law firm,”  said Firm CEO Michelle Foster.

Filed Under: News Tagged With: Andrew Silverman, Brian Forgue, Brian Nagle, Caroline Donato, Harry DiDonato, Joseph Bellinghieri, Kristen Matthews, Lance Nelson, Lindsay Dunn, Louis Teti, Patrick Gallo, Robert Burke, Tim Rayne, William Gallagher

Taxation of Foreign Investment in Delaware Entities

January 9, 2020 by Andrew R. Silverman, Esq.

Foreign investors and entrepreneurs who would like to do business in the United States are confronted with a number of legal decisions to make and, if not familiar with the local law, these decisions can be quite daunting. One question that invariably comes up for foreign investors who desire to form a Delaware entity is this: how will it be taxed?

Is the income taxable? 

Your entity will be taxed if two conditions are present: (1) the entity is engaged in the sale of goods and services in the United States (referred to as “engaged in trade or business” or “ETB”); and (2) the entity earns income that is effectively connected with United States sources (such income, is often referred to as “effectively connected income” or “ECI”).

TIP: If your entity is subject to taxation in the United States, you may be able to offset the taxes by carefully planning how distributions will be made to the ultimate beneficial owner (i.e., the foreign shareholders or partners) and by taking advantage of the numerous tax treaties to which the United States is a party.

Taxation of Delaware C-Corporations

Federal Taxation

If your entity is a corporation and is subject to tax in the United States, it will be subject to double taxation. This means that the ECI will be taxed once upon receipt by the corporation and then a second time if it is later distributed to stockholders (such as through a dividend or liquidation). The current federal corporate tax rate is 21 percent of the ECI.

Delaware Taxation

Generally, Delaware will only assess a tax on ECI that is attributable to Delaware sources or if it has assets, employees, or activities in Delaware.

Taxation of Delaware LLCs and Partnerships

Federal Taxation

Generally, the federal government does not impose a tax on ECI that is received by the LLC or partnership but it does tax the members or partners directly. Thus, while an LLC or partnership can avoid double taxation, the members or partners will be exposed to federal and state and local taxes and will need to file US tax returns that report worldwide income. This may not be ideal for various reasons.

In such cases, each member or partner may form a “blocker” corporation to hold its membership or partnership interest. In such cases, the blocker corporation and dividends to its ownership will be taxed but reporting requirements on the ultimate beneficial owner will be reduced.

Delaware Taxation

Delaware does not impose income taxes upon LLCs and partnerships; however, the state will impose a gross receipts tax on income from Delaware sources.

Any foreign person or entity that desires to do business in the United States through a Delaware entity is advised to partner with US-based lawyers and accountants who are familiar with the legal and tax requirements.


Andrew Silverman is an attorney in the firm’s Business Department whose practice includes complex corporate governance and financing matters. If you are a Delaware business owner and desire guidance, call (610) 840-0286 or email asilverman@macelree.com.

Filed Under: Articles by Our Attorneys Tagged With: Andrew Silverman, Delaware Business, tax law

  • Page 1
  • Page 2
  • Go to Next Page »

Primary Sidebar

Footer

(610) 436-0100

LEGAL SERVICES

ABOUT US

NEWS & INSIGHTS

OFFICES

Centreville, DE

5721 Kennett Pike
Wilmington, DE 19807
302-654-4454
Learn More

Kennett Square, PA

209 East State Street Road
Kennett Square, PA 19348
610-444-3180
Learn More

West Chester, PA

17 West Miner Street
West Chester, PA 19382
610-436-0100
Learn More

  • Terms of Use
  • Privacy Policy
  • Disclaimer
  • Staff Only
  • Careers

© 2026 and all rights reserved by MacElree Harvey, Ltd.