• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer
MacElree Harvey, Ltd.

MacElree Harvey, Ltd.

Initiative in Practice

  • Home
  • Legal Services
        • Banking & Finance Law
        • Business & Corporate Law
        • Criminal Defense
        • Employment Law
        • Estates & Trusts Law
        • Family Law
        • Litigation Law
        • Mediation and Arbitration
        • Personal Injury Law
        • Real Estate & Land Use Law
        • Tax Law
  • Our Team
        • Joseph A. Bellinghieri
        • Hiruy Y. Berhane
        • Patrick J. Boyer
        • Krzysztof M. Bozentka
        • Jeffrey P. Burke
        • Robert A. Burke
        • Matthew C. Cooper
        • Marie I. Crossley
        • Pilar Diaz
        • Harry J. DiDonato
        • Jaycie DiNardo
        • Caroline G. Donato
        • Nicholas S. Eisel
        • Sally A. Farrell
        • Brian J. Forgue
        • William J. Gallagher
        • Patrick J. Gallo, Jr.
        • Mary Kay Gaver
        • J. Charles Gerbron, Jr.
        • Leo M. Gibbons
        • Joseph P. Green, Jr.
        • Frank W. Hosking III
        • Katherine A. Isard
        • Peter E. Kratsa
        • Mary E. Lawrence
        • Daniel R. Losco
        • Michael G. Louis
        • John F. McKenna
        • Matthew M. McKeon
        • Lou Mincarelli
        • Brian L. Nagle
        • Lance J. Nelson
        • Timothy F. Rayne
        • Michael C. Rovito
        • Duke Schneider
        • Andrew R. Silverman
        • Ashley B. Stitzer
        • Patrick L. Ware
        • Jeremy A. Whalen
        • Natalie R. Young
  • About Us
    • Our History
    • Our Approach
    • Social Responsibility
    • Testimonials
  • Careers
  • News & Updates
    • Articles by Our Attorneys
    • News
    • Podcasts
    • Videos
    • Newsletters
  • Offices
    • Centreville, DE
    • Kennett Square, PA
    • West Chester, PA
  • Contact
  • (610) 436-0100

News

Tax Uncertainty Abounds As 2020 Presidential Election Approaches

September 30, 2020 by MacElree Harvey, Ltd.

The November 3rd general election is just a month away, and while the impact of the COVID-19 pandemic is likely to dominate the fiscal policy debate this election cycle, each presidential candidate has also introduced a number of competing tax proposals. The outcome of this election therefore has the potential to shape the tax code for both businesses and individuals for years to come. Although it is impossible to predict what will happen this November, we are carefully monitoring the proposed tax law changes and are ready to implement a number of tax-planning strategies tailored to your specific needs. Key elements of the candidates’ tax proposals are outlined below.

Biden’s Proposals:

Former Vice-President Joe Biden has proposed a variety of federal tax law changes in response to President Trump’s 2017 Tax Cuts and Jobs Act (“TCJA”), including the following proposals:

– Repeal the TCJA’s individual income tax cuts for taxpayers with income above $400,000 (i.e. back to the 39.6% tax rate).
Cap the value of itemized deductions to 28%.
Tax capital gains and dividends at the same rate as ordinary income for taxpayers with over $1,000,000 in income.
– Raise the corporate income tax rate from 21% to 28%.
– lnstitute a 15% alternative minimum tax on corporations with $100 million or more in profits.
– Raise the Global lntangible Low Tax lncome (‘GlLTl’) (a tax on income from foreign affiliates, including foreign-held intangible property and its related income) rate from 10.5% to 21%.
– Eliminate the automatic step-up in basis and tax unrealized capital gains at death. (We also assume that Biden would mandate the Federal Estate and Gifi Tax Exemption to o return to a pre-TCJA base of $5 million per individual.)
– lnstitute a 12.4% Social Security payroll tax, to be split between employers and employees, on income earned in excess of $400,000.
– Raise the Child Tax Credit, expand the Earned lncome Tax Credit, and enact new tax credits for certain family caregivers, first-time home buyers, and renters.
– Exclude forgiven student loan debt from taxable income.

Trump’s Proposals:

President Trump has generally expressed his intent to cut taxes and to preserve and expand on the TCJA, which includes the following proposals:

– Keep the top 37% tax rate right as is. ln addition, implement a 10% rate cut for middle- income taxpayers, effectively lowering the 22% rate to 15%.
– Make the TCJA changes for itemized deductions and the higher basic standard deduction permanent.
– Reduce tax rates for capital gains, index gains for inflation, and create a capital gains tax holiday for a limited time.
– Require a Social Security number for taxpayers to be eligible for the Child tax Credit or Dependent Credit.
– Enact the Education Freedom Scholarship tax credit, which would provide up to $5 billion worth of income tax credits annually for individual and corporate donations to state-identified not-for-profit scholarship-granting organizations.
– Preserve the current corporate tax rates under the TCJA.
– Preserve the higher Estate and Gift Tax Exemption and keep the current rules relating to the step-up in basis.
– The President recently issued an executive order that postpones Social Security tax for employees for September 1 through the end of 2020. He has said that this relief could turn into a permanent extension.

Ultimately, the outlook for legislative action in 2021 on tax proposals will depend on who is elected president and which party controls the House and Senate. Trying to guess how and when the tax code will change and planning for those changes now is an impossible task. Still, taxpayers should keep these proposals in mind when considering selling property, engaging in family tax and estate planning, or making business and investment decisions. We are constantly monitoring these proposed changes and are prepared to assist you regardless of what happens this November.

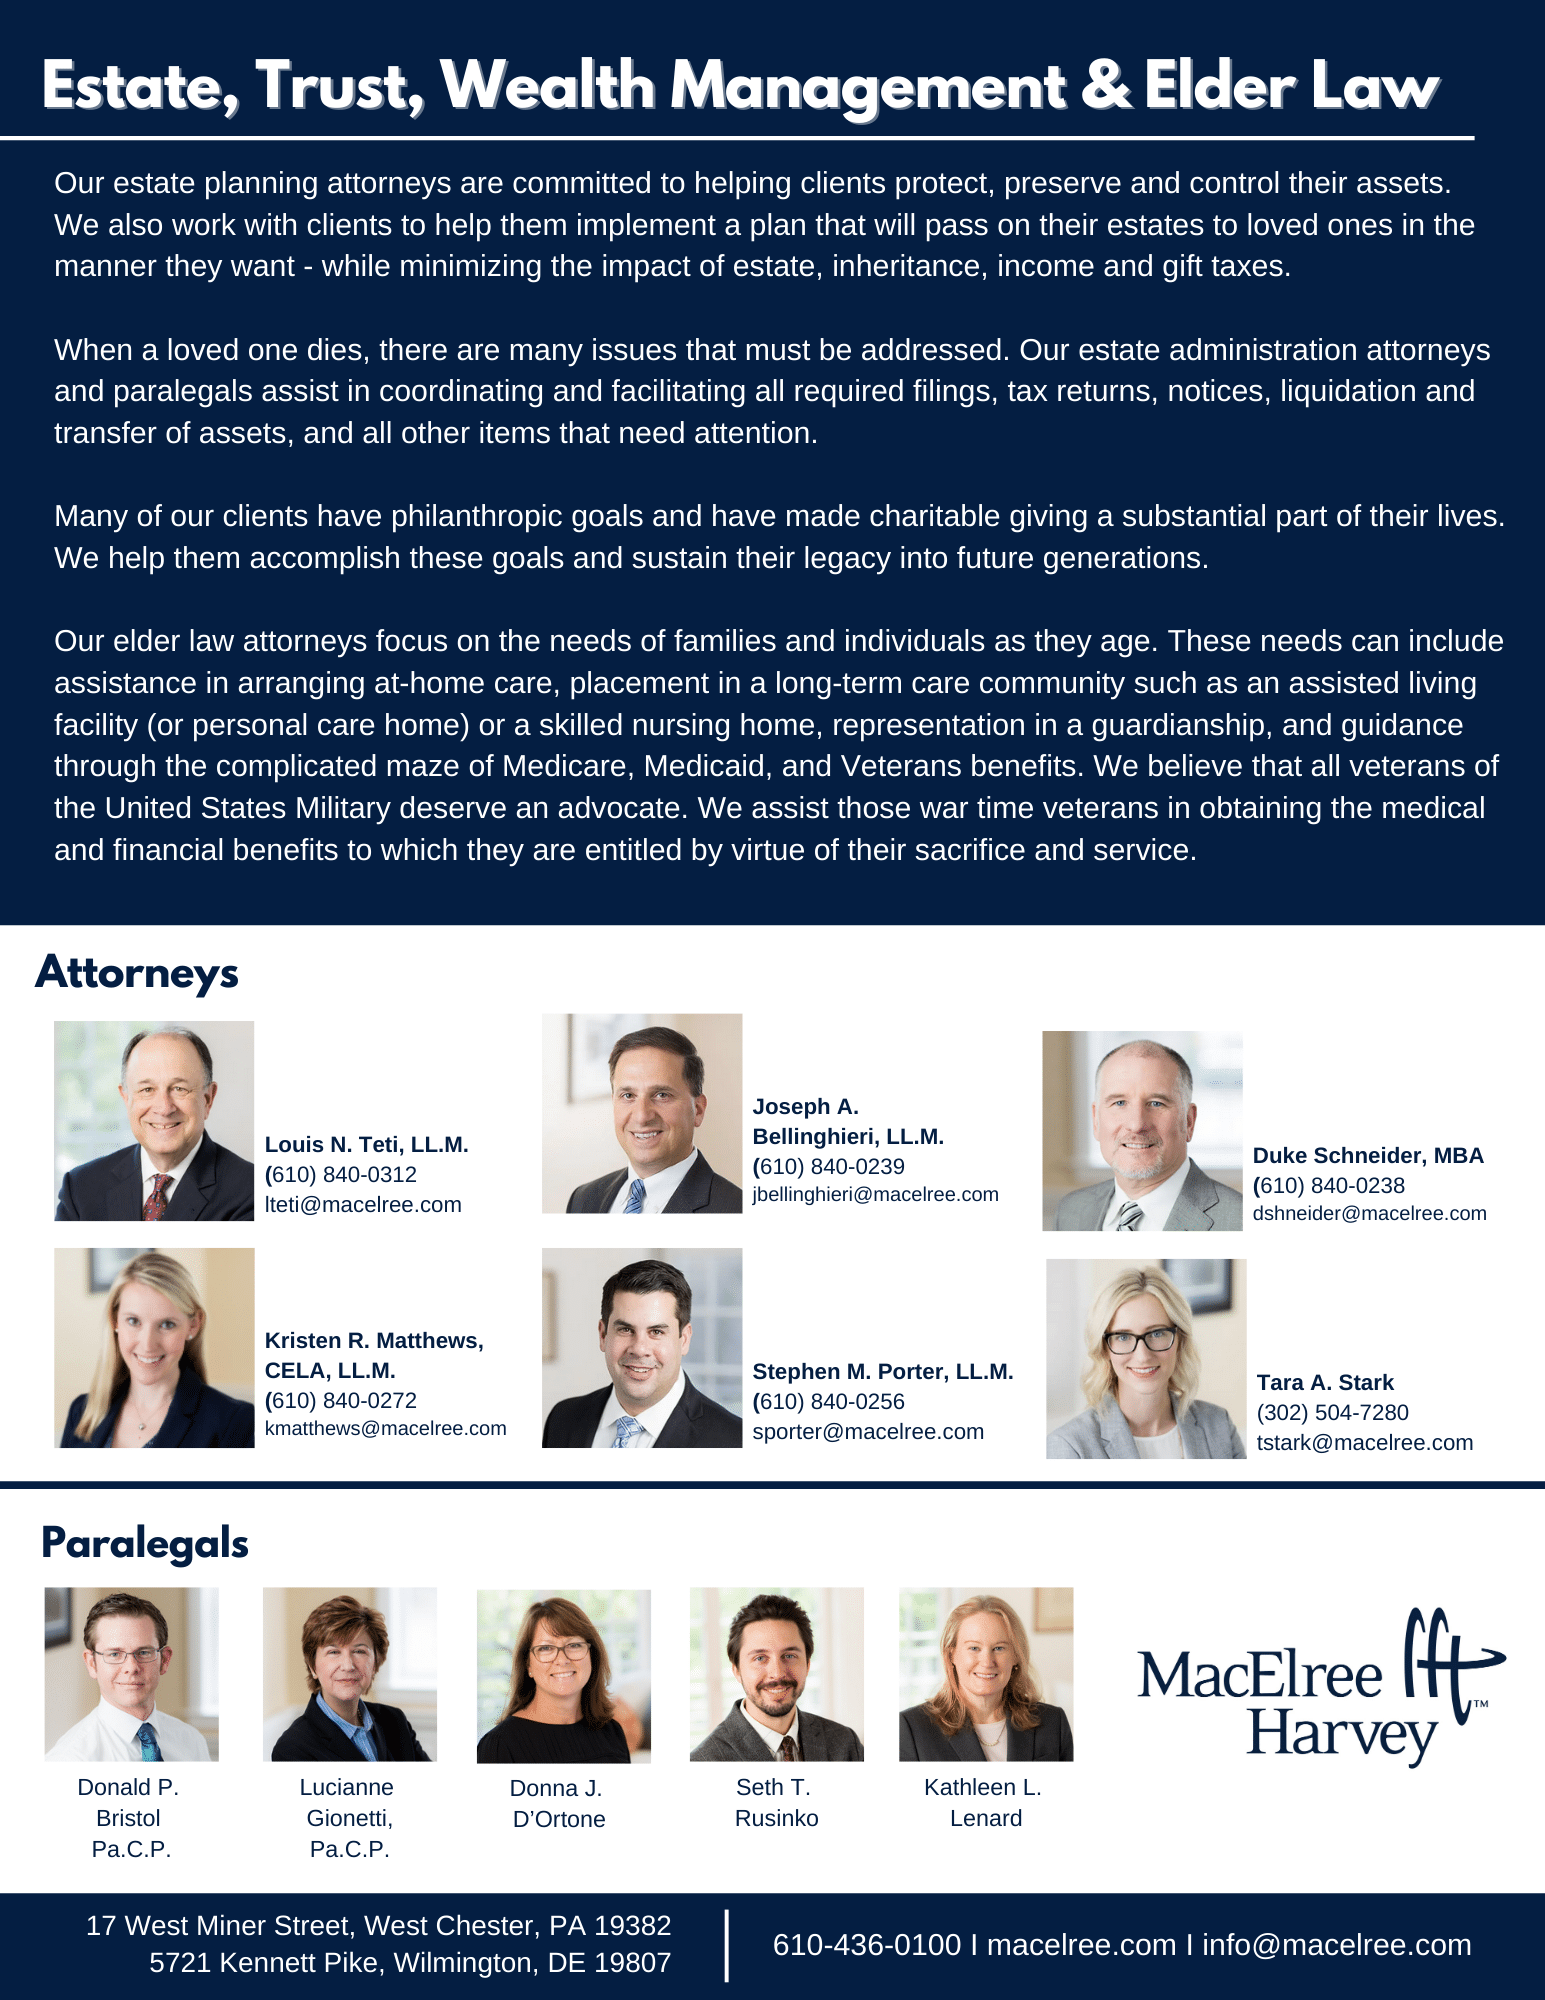
Give us a call today (Louis N. Teti (610) 840-0312; Joseph A. Bellinghieri (6i0) 840-0239; Duke K. Schneider (610) 840-0238; Kristin R. Matthews (610) 840-0272; Stephen M. porter (610) 840-0256; or, Tara A. Stark (302) 504-72801 to schedule an appointment to discuss how you might be impacted by the proposed tax law changes, and actions to consider in light of these proposals.
Filed Under: News

Attorney Tim Rayne Appears on Lawyer2Lawyer Network Radio Show

September 28, 2020 by MacElree Harvey, Ltd.

On September 19, 2020, Pennsylvania Car Accident Attorney Tim Rayne was a special guest on the Lawyer2Lawyer Network Radio Show on 1210 am Radio in Philadelphia along with his friend and colleague JB Disheimer from Stampone Law talking about “A Lawyer’s Guide to Purchasing Car Insurance”.

Click here to listen.

During the Radio Show, Tim and JB discussed the critically important choices you make when purchasing Car Insurance in Pennsylvania like choosing Full Tort not Limited Tort, purchasing significant Uninsured and Underinsured Coverage, having enough Liability Coverage to protect your Assets and thinking about having increased Medical Coverage just to name a few.

Tim Rayne wrote a book on this topic, A Lawyer’s Guide to Purchasing Car Insurance that is available for free download and in video form at www.TimRayneLaw.com, and for purchase on Amazon.

Filed Under: News Tagged With: Timothy F. Rayne

Center For Disease Control Issues Temporary Halt of Residential Evictions To Prevent The Further Spread of COVID-19

September 4, 2020 by MacElree Harvey, Ltd.

On September 1, 2020, the CDC issued an Order that becomes effective September 4, 2020 prohibiting the eviction of any covered person from any jurisdiction to which this Order applies which is basically the United States.

However, a covered person means any tenant or resident of a residential property who provides to their landlord, the owner of the residential property or other person with a legal right to pursue eviction or a possessory action, a declaration under penalty of perjury indicating that:

1. The individual has used best efforts to obtain all available government assistance for rent or housing;

2. The individual either expects to earn no more than $99,000.00 in annual income for 2020 or no more than $198,000.00 if filing a joint tax return, was not required to report any income in 2019 to the IRS or received an economic impact (stimulus check) pursuant to Section 2201 of the CARES Act;

3. The individual is unable to pay the full rent or make a full housing payment due to substantial loss of household income, loss of compensable hours of work or wages, a layoff, or extraordinary out of pocket medical expenses;

4. The individual is using best efforts to make timely partial payments that are as close to the full payment as the individual’s circumstances may permit, taking into account other non-discretionary expenses; and

5. Eviction would likely render the individual homeless or force the individual to move into and live in close quarters. This Order does not include foreclosure on a home mortgage. These persons are still required to pay rent and follow all other terms of their lease and rules of the place where they live. The temporary halt on evictions runs through December 31, 2020.

Criminal Penalties

A person violating this Order may be subject to a fine of no more than $100,000.00 if the violation does not result in death or one year in jail or both or a fine of no more than $250,000.00 if the violation results in a death or one year in jail or both. An organization violating this Order may be subject to a fine of no more than $200,000.00 per event if the violation does not result in death or $500,000.00 per event if the violation results in death or as otherwise provided by law.

The CDC Order provides an Affidavit for the tenant to sign stating that under penalty of perjury they have satisfied the requirements of the Order.

It is my understanding that until the tenant provides the landlord with a copy of the signed Affidavit that the landlord may still evict the tenant. However, once they are given that Affidavit the landlord may not evict the tenant although they may sue the tenant for back rent and obtain a judgment for money since the Order explicitly says it “has no effect on the contractual obligations of renters to pay rent and shall not preclude charging or collecting fees, penalties or interest as a result of the failure to pay rent or other housing payment on a timely basis.”

Filed Under: News

Southeast PA Liquor Licensees May Apply for Temporary Extension of Licensed Premises to Serve Alcohol Outside

June 9, 2020 by MacElree Harvey, Ltd.

By: Matthew M. McKeon

*Note: due to the rapidly evolving government response to the COVID-19 pandemic, this article may not be current at the time it is read. Readers seeking additional information may contact the author at mmckeon@macelree.com.

On June 3, 2020, the Pennsylvania Liquor Control Board (the “LCB”) issued a press release  and the second revised Advisory Notice No. 26 announcing that liquor licensees could apply for a temporary extension of their licensed premises to include additional outdoor areas.  This would allow licensees to legally sell and serve alcohol to patrons in these outdoor areas.  The LCB’s announcement follows Governor Wolf’s May 27, 2020 guidelines allowing restaurants in counties which are in the “yellow” phase of the Commonwealth’s COVID-19 reopening process to begin dine-in service in outdoor areas on June 5, 2020.

Licensees are advised to read the LCB’s press release and the second revised Advisory Notice No. 26 to learn all relevant information regarding this application.  Important aspects of this temporary measure include the following:

  • Applicable licenses: This application is available to licenses for restaurants, hotels, clubs, catering clubs, retail dispensers, distilleries, limited distilleries, wineries, limited wineries, and breweries.
  • Outdoor Areas Affected: The temporary extension of the premises only applies to outdoor areas immediately adjacent to, abutting and contiguous to the existing licensed premises. This excludes any outdoor areas which are separated from a licensed premises by a public thoroughfare. If the outdoor area to be licensed is not under the licensee’s control (for example, a municipal sidewalk) then the licensee must provide proof of their right to occupy the area (such as a permit or other authorization from the municipality).
  • Automatic Authorization Upon Posting of Printed Confirmation Page:  After the licensee submits the application on the LCB’s website (see instructions below) the licensee will see a confirmation screen stating that the application was successfully submitted for processing. The licensee shall print and post this confirmation screen as directed, whereupon they will automatically have temporary authority to operate on the proposed outdoor area. The licensee will also be directed to post a Notice of Application. Distilleries, limited distilleries, wineries, limited wineries and breweries do not need to post a Notice of Application but must display the LCB’s email stating the application was accepted.
  • Duration: The initial authority for a temporary extension will last until one of the following occurs: (1) the COVID-19 Emergency Declaration ends; (2) the LCB receives a protest or petition to intervene in opposition to a particular application; or (3) the LCB informs the licensee that the authority has otherwise come to an end.  However, licensees can also apply for a permanent extension of the licensed premises under the normal procedures.
  • Plan Required: Like an application to permanently extend the licensed premises, the licensee seeking a temporary extension must also submit a plan of the outdoor area as directed by the online application.
  • No Fee for Temporary Extension Application: However, the normal application fee applies if the licensee is applying for a permanent extension of the licensed premises.

Licensees can apply by logging into the LCB website, clicking “Other Licenses Changes / Amendments” under the “Existing Licenses” section, selecting their license, and scrolling to “EMERGENCY TEMPORARY EXTENSION”.  Licensees will then be prompted to answer questions and submit the necessary plan to complete their application.

If you are unsure about any aspect of the LCB’s temporary extension of premises application or have other questions about the implications of the COVID-19 pandemic on your license, please contact MacElree Harvey, Ltd. by emailing Matthew McKeon at mmckeon@macelree.com. This article provides a general overview of the law. It is not intended to be, and should not be construed as, legal advice for any particular fact situation.

Filed Under: News

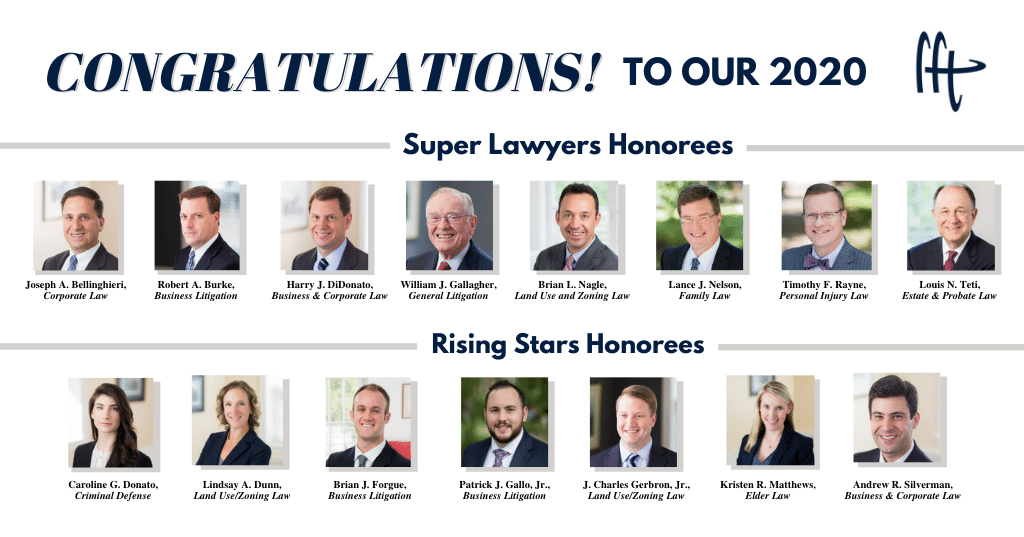
15 MacElree Harvey Attorneys Named to Prestigious 2020 Super Lawyers/Rising Stars List

June 1, 2020 by MacElree Harvey, Ltd.

MacElree Harvey is pleased to announce the selection of 15 of its Pennsylvania attorneys to the prestigious list of Pennsylvania Super Lawyers or Rising Stars.

Super Lawyers is a rating service of outstanding lawyers operated by legal publisher Thompson Reuters which rates attorneys in more than 70 practice areas who attain a high degree of peer recognition and professional achievement.

Super Lawyers uses a patented multi-faceted selection process involving peer nominations, independent research regarding 12 indicators of professional achievement, peer evaluation by a Blue Ribbon Panel, and final selection.

Attorneys under age 40 or practicing less than 10 years are eligible for designation as Rising Stars and only 2.5 percent of eligible attorneys are selected.  In 2020, MacElree Harvey’s rising stars were:

  • Caroline Donato – Criminal Law
  • Lindsay Dunn – Land Use/Zoning
  • Brian Forgue – Business Litigation
  • Patrick Gallo – Business Litigation
  • Charles Gerbron – Land Use/Zoning
  • Kristen Matthews – Elder Law
  • Andrew Silverman – Business/Corporate Law

The Super Lawyers list is limited to only 5 percent of the eligible attorneys. MacElree Harvey’s 2020 Pennsylvania Super Lawyers were:

  • Joseph Bellinghieri – Estate and Probate
  • Robert Burke – Business Litigation
  • Harry DiDonato – Business/Corporate Law
  • William Gallagher – General Litigation
  • Brian Nagle –  Land Use/Zoning
  • Lance Nelson – Family Law
  • Tim Rayne – Personal Injury
  • Louis Teti – Estate and Probate

Harry DiDonato and Lance Nelson earned special designations in 2020 because they have been named as Super Lawyers for the last 10 years.

Tim Rayne was named as a Top 100 Super Lawyer in Pennsylvania.

“The firm is honored and humbled to have more of our attorneys named to the 2020 Super Lawyer/Rising Star list than any other Chester county-based law firm,”  said Firm CEO Michelle Foster.

Filed Under: News Tagged With: Andrew Silverman, Brian Forgue, Brian Nagle, Caroline Donato, Harry DiDonato, Joseph Bellinghieri, Kristen Matthews, Lance Nelson, Lindsay Dunn, Louis Teti, Patrick Gallo, Robert Burke, Tim Rayne, William Gallagher

Congratulations, Caroline!

May 15, 2020 by MacElree Harvey, Ltd.

We are pleased to announce that Caroline Donato has earned her LL.M. in Trial Advocacy from Temple University’s Beasley School of Law. Caroline has graduated with Honors from this program.

Caroline joined the Firm’s Business Department in 2014, then transitioned into Criminal Defense. Since then Caroline has been named a Main Line Top Lawyer for the last five years, Super Lawyers Rising Star in 2018 and 2019, Chester County Chamber of Business and Industry’s Women Influencing Business Rising Star of the Year in 2019, Chair of the Next Generation Committee of the Pennsylvania Association of Criminal Defense Lawyers (“PACDL”) since 2018, and an active member of PACDL’s CLE committee since 2018.

The Temple LL.M. in Trial Advocacy was the first program of its kind in the country. U.S. News & World Report has ranked this program among the top three trial advocacy programs in the country for more than twenty years.

Filed Under: News Tagged With: Caroline G. Donato

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 19
  • Page 20
  • Page 21
  • Page 22
  • Page 23
  • Page 24
  • Go to Next Page »

Primary Sidebar

Footer

(610) 436-0100

LEGAL SERVICES

ABOUT US

NEWS & INSIGHTS

OFFICES

Centreville, DE

5721 Kennett Pike
Wilmington, DE 19807
302-654-4454
Learn More

Kennett Square, PA

209 East State Street Road
Kennett Square, PA 19348
610-444-3180
Learn More

West Chester, PA

17 West Miner Street
West Chester, PA 19382
610-436-0100
Learn More

  • Terms of Use
  • Privacy Policy
  • Disclaimer
  • Staff Only
  • Careers

© 2026 and all rights reserved by MacElree Harvey, Ltd.